A Philippine packaging importer recently described a familiar problem: they were paying a Chinese supplier through a BPI telegraphic transfer in USD and wanted to know whether settling the invoice in RMB would cost less. Another buyer had already found and verified a manufacturer on 1688, then faced the harder question of how to pay the factory directly without losing the savings to conversion and card fees.
Those are real payment decisions, not theoretical currency questions. A Philippine business can pay a Chinese supplier in USD or RMB when the invoice, sending institution, receiving bank, and supplier account support the route. The cheaper option is the one that uses fewer pesos to settle the same commercial obligation, with the supplier receiving the amount due.
Count three things: pesos out, USD or RMB received, and the protection you give up by paying directly.
Main takeaways
- Compare the total PHP debit and the supplier's expected receipt, not the transfer fee by itself.
- USD often works when the invoice and receiving account are already in USD. RMB deserves a quote when the supplier prices domestically and expects an exact local-currency amount.
- A bank telegraphic transfer remains a valid route, but its FX rate and possible bank deductions can matter more than the advertised service charge.
- Direct payment can reduce processing costs while removing marketplace dispute protection. Keep the payment decision separate from the decision to trust the order.
- Ask for the document checklist early. Import-related payments can require the invoice, purchase records, beneficiary information, and other supporting evidence.
These discussions surface the questions importers need answered before they send the payment:
- I've verified the manufacturer. What is the safest and most cost-effective way to pay the factory directly?
- Should I pay the invoice in USD or RMB after all conversion and bank charges are included?
- Is a Philippine bank telegraphic transfer still competitive for this order size?
- What payment protection do I lose if I move the transaction outside Alibaba or another protected marketplace?
The published replies are anecdotal, so this article does not use them as rate or regulatory evidence. The questions themselves show where importers get stuck after the sourcing work is done.
Start with the invoice, not a currency converter
The commercial invoice tells you what the supplier is asking you to settle. The receiving account tells you what the supplier's bank can accept. Check both before comparing rates.
If the supplier is willing, ask for two quotations for the same order and delivery terms: one showing the exact USD amount and USD receiving account, and another showing the exact RMB amount and RMB receiving account. A consumer currency converter cannot tell you which route the bank will use, which charges may be deducted, or whether the beneficiary can receive that currency without another conversion.
| Decision point | Paying in USD | Paying in RMB |
|---|---|---|
| Best fit | The supplier invoices in USD and can receive USD into the named business account. | The supplier invoices in RMB and expects an exact local-currency amount. |
| Conversion | Your business may convert PHP to USD. The supplier may later convert USD to RMB. | Your payment route converts into RMB before the supplier receives it. |
| Main cost risk | A supplier-side conversion buffer plus sender, correspondent, or recipient charges. | An unattractive direct rate, route charge, or an unintended intermediate conversion. |
| Amount certainty | Confirm whether deductions can leave the USD payment short. | Confirm the exact RMB amount expected to reach the supplier account. |
| Operational check | Verify that the supplier actually wants USD and owns the receiving account. | Verify that the provider supports the commercial CNY route and the receiving bank can accept it. |
When USD may be the better choice
USD can make sense when the contract and invoice are already in USD, the beneficiary account is meant to receive dollars, and your business can fund the payment at an acceptable rate.
It may also be cleaner when the available RMB option still routes through USD. Changing the displayed payout currency does not prove that an intermediate conversion disappeared. Ask the bank or provider to show the route and the expected supplier receipt.
Some manufacturers manage USD receipts routinely and quote competitively in dollars. Asking for RMB will not automatically produce a discount.
When RMB may be the better choice
RMB may be more efficient when the supplier prices domestically in RMB, pays its own costs in RMB, and offers a genuinely lower RMB quote rather than converting the USD price at a padded rate.
The beneficiary should be the supplier named on the invoice or another documented entity with a legitimate role in the transaction. Your bank or payment provider still needs to accept the receiving account, currency, payment purpose, and supporting documents.
Bank of China Manila identifies itself as the Philippines' designated RMB clearing bank and says it supports RMB settlement, remittance, foreign exchange, and related services for participating institutions. RMB infrastructure therefore exists locally. Access is still transaction-specific. The existence of a clearing bank does not make every business payment eligible.
The hidden time cost of a branch-based transfer
For many Philippine SMEs, paying an overseas supplier is still a physical errand. Someone travels to the bank, completes a telegraphic-transfer application, submits the invoice and supporting documents, waits for the branch to review the request, and returns to the office without knowing exactly when the supplier will receive usable funds.
Not every transaction requires a branch visit. Some banks accept eligible outward-remittance requests online. Document-heavy payments can still be sent back to a branch, however, and the processing window may begin only after the bank accepts a complete request. BPI, for example, directs customers with certain BSP-registered documents to a branch and gives an indicated processing period of three to five banking days for its outward-remittance service.
The bank's processing time is only part of the delay. Travel, traffic, parking, the branch queue, document review, and form completion can consume one to three hours or more. The timing varies by location, day of the week, and how busy the branch is. If the beneficiary name, account number, SWIFT/BIC, bank address, payment purpose, or supporting document is incomplete or entered incorrectly, the payment may be held until the information is corrected. A problem that crosses a cut-off, weekend, or holiday can turn into a delay of a week.
That delay affects the shipment, not just the finance team. A supplier that releases goods only after confirming receipt cannot ship while the payment is still being reviewed or corrected.
| Workflow point | Traditional branch-based transfer | Quotable Payments |
|---|---|---|
| Initiation | Travel to a branch, complete the bank's forms, and submit the required documents. | Review and submit an eligible supplier payment online. |
| Rate review | The final applied rate may differ from an earlier estimate or indicative quote. | The available rate can be refreshed on demand, approximately every 30 seconds while the quote is active. |
| Delivery timing | Processing may take several banking days and can move later when information or documents need correction. | An eligible, funded, and approved route may reach the supplier on the same or next business day, depending on cut-offs and route conditions. |
| Operational effect | The supplier may wait several days for confirmed receipt before releasing the shipment. | Earlier receipt can allow the supplier to release inventory sooner when every commercial condition has been met. |
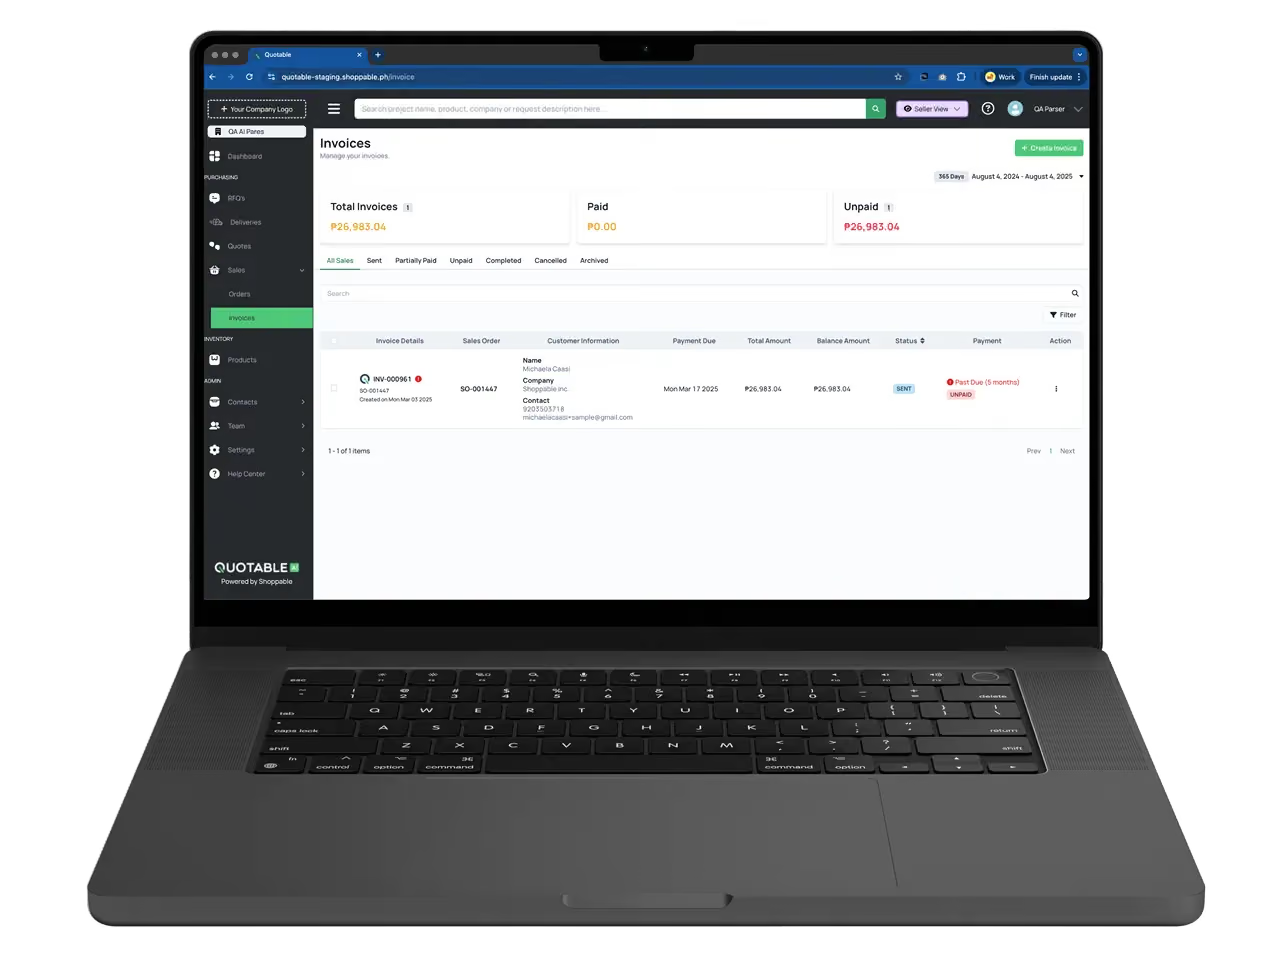
Quotable Payments removes the branch visit for an eligible approved payment. The business can review the available route, rate, fees, Recipient details, and estimated payout online before submitting. While an active quote is being reviewed, the rate can be refreshed on demand approximately every 30 seconds.
For eligible routes submitted with complete information, sufficient funding, and approval before the relevant cut-off, the supplier may receive funds on the same or next business day. That is not a universal settlement guarantee. Currency, route, time zone, holidays, compliance review, intermediary processing, and the receiving bank can all change the delivery estimate.
The potential gain is larger than the time saved on the branch visit. Moving from a multi-day payment process to an eligible same- or next-business-day route can let the supplier release inventory earlier. The shipment still depends on the supplier confirming usable funds and satisfying the order's other commercial conditions.
What a bank telegraphic transfer actually costs
A telegraphic transfer is familiar and widely accepted. For an established supplier relationship, it may be entirely sensible. Its service charge is not the full cost.
| Provider | PHP to USD wire fee | USD settlement time | PHP to RMB wire fee | RMB settlement time |
|---|---|---|---|---|
| AUB | USD20.50: USD15 cable plus USD5.50 commission, plus DST of PHP0.60 per PHP200 when peso-funded | Not publicly stated | No route-specific PHP-funded CNY tariff published | Not publicly stated |
| BDO | USD10 service fee plus USD25 overseas/intermediary charge; other receiving-bank charges may apply | 3–5 banking days | No comparable PHP-funded CNY tariff published; request a branch quote | Not publicly stated for direct PHP-to-CNY |
| Quotable Payments | Zero wire fees; the FX rate is shown before approval | Same day to next banking day | Zero wire fees; the FX rate is shown before approval | 1 banking day |
| Metrobank | Not publicly itemized; the transfer form lists commission, DST, cable, correspondent and other possible charges | Not publicly stated | Not publicly itemized; request a route-specific quote | Not publicly stated |
| UnionBank | USD40 online SWIFT fee including correspondent and cable charges; online SWIFT requires a USD account, so PHP funding is branch-quoted | 3–5 banking days | Non-USD transfer requires a branch; CNY fee is not publicly stated | Not publicly stated |
| Security Bank | USD20 commission plus DST when peso-funded; add USD15 when the remitter pays correspondent charges under OUR | Within 3 banking days | USD20 commission plus DST when peso-funded; add CNY55 under OUR | Within 3 banking days |
| BPI | PHP600 service charge plus DST of PHP0.60 per PHP200; correspondent and beneficiary-bank charges vary | 3–5 banking days | Same published service-charge and DST basis; a PHP-funded CNY transfer is handled through a branch and other bank charges vary | 3–5 banking days |
The bank rows use the latest route-specific figures available in the linked official material as of 31 October 2026. “Not publicly stated” means the bank did not publish a comparable PHP-funded fee or settlement commitment for that route in the material reviewed; it does not mean the route is unavailable. Bank processing estimates assume complete documents, correct beneficiary details, and submission before the applicable cutoff. FX spreads, DST, correspondent-bank charges, beneficiary-bank deductions, and charge instructions can change the all-in cost.
BPI's published remittance-fee schedule, reviewed for this draft in October 2026, lists a PHP600 service charge for a remittance funded from a peso account plus documentary stamps of PHP0.60 for every PHP200. Correspondent, intermediary, and beneficiary-bank charges can vary. Some may be deducted from what the supplier receives. BPI says the fees can change without prior notice.
On a PHP500,000 illustrative payment, those two fixed published items alone would be:
- Service charge: PHP600
- Documentary stamps: PHP500,000 / PHP200 × PHP0.60 = PHP1,500
- Subtotal before FX and other bank charges: PHP2,100
The PHP2,100 subtotal excludes the difference between the bank's applied rate and your comparison benchmark. It also excludes variable correspondent and beneficiary-bank deductions.
BPI's outward-remittance page describes its displayed computation as estimated, says the provided rate is subject to change, and gives an indicated processing period of three to five banking days. Your decision has to use the final quote and route terms presented for the actual payment.
Compare the quote the way an importer would
Get the USD and RMB quotes close together in time. Put the following fields in one sheet:
- Total PHP debit
- Currency and amount the supplier is expected to receive
- Applied exchange rate
- Transfer charges, documentary taxes, and stamps
- Possible correspondent or beneficiary-bank deductions
- Expected delivery window and payment status visibility
- Whether the quote is indicative or final
All-in payment cost = total PHP debit + charges paid separately
A route that debits fewer pesos but leaves the supplier short has not saved money. It has moved the cost into a second transfer, a delayed shipment, or an argument over who absorbs the difference.
Annual payment cost = all-in cost per payment × expected payments per year
Run the annual calculation for recurring purchases. A rate difference that looks small on one deposit can become material across monthly deposits and final balances.
For a broader comparison of SWIFT, local rails, cards, letters of credit, and payment platforms, use the guide to paying overseas suppliers. This article stays with the Philippines-to-China currency decision.
Documents and commercial risk belong in the same decision
The Bangko Sentral ng Pilipinas' foreign-exchange rules recognize several import-payment arrangements, including letters of credit, documents against payment, documents against acceptance, open-account arrangements, direct remittance, advance payment, and qualifying digital payments through ecommerce participants.
The BSP also maintains minimum documentary requirements for foreign-exchange sales related to import transactions. The exact checklist and submission process depend on the arrangement and the institution handling the FX sale. A practical payment file can contain the commercial invoice, purchase order or contract, payment purpose, supplier legal details, beneficiary account and bank information, intermediary instructions when applicable, shipping or import records, and internal approval.
The FX Manual allows electronic submission under the institution's procedures, while preserving the institution's ability to request originals or copies for verification. Get the checklist before the due date. Discovering a missing document after the supplier has reserved production time is avoidable.
The payment rail does not protect the goods. Moving an early order outside Alibaba Trade Assurance or another protected channel may reduce processing cost while removing a dispute process. A cheaper transfer can still be the worse commercial decision.
Before paying directly, independently confirm the supplier's legal entity and match it to the beneficiary name. Verify the bank details through a known contact using a separate channel, especially after any last-minute account change. Keep the approved sample, contract, inspection rights, and milestones with the payment record. When staged terms are available, they give you more leverage than a small difference in transfer fees.
For broader factory verification, contracts, inspections, and landed-cost planning, use the separate China sourcing guide. This article is intentionally limited to the payment decision.
A six-step payment decision
- Read the formal invoice. Confirm whether the obligation is due in USD or RMB. A chat message should not override the document your finance team will reconcile.
- Verify the receiving account. Check the beneficiary name, account number, bank, SWIFT/BIC, address, currency, and intermediary instructions. Make sure the account can receive the chosen currency.
- Request comparable quotes. Ask for the total PHP debit and the expected supplier receipt for every valid route, with quotes taken at roughly the same time.
- Find the deductions. Establish which charges you pay and which may come out of the supplier's amount. An exact-amount invoice needs an exact-amount payment plan.
- Price the lost protection. Decide whether the order should remain inside a protected marketplace, use staged terms, require an inspection, or use another trade-finance arrangement.
- Keep the record together. Save the invoice, supplier details, quote, approval, confirmation, and proof of receipt. Reconcile the actual PHP debit and fees against the purchase order.
Where Quotable Payments may fit
Quotable Payments is relevant when an eligible business wants to see the available route, final quote, fees, Recipient details, and estimated payout before submitting an approved supplier payment. The payment context can stay linked to its invoice, purchase order, or approval record.
Currency, country, receiving method, timing, and route availability depend on the business, jurisdiction, Recipient, and approved setup. Confirm whether the required USD or CNY route is currently available during onboarding.
Review your supplier-payment requirements
Share the currencies, supplier country, typical payment amount, and expected volume. The payments team will confirm current availability and explain the applicable onboarding steps.
FAQs About Paying Chinese Suppliers from the Philippines
Is paying a Chinese supplier in RMB always cheaper than paying in USD?
No. RMB is cheaper only when the supplier's RMB price and the available payment route produce a lower total PHP cost for the required supplier receipt. Compare both quotes at the same time and include every disclosed fee and deduction.
Can a Philippine business pay a 1688 manufacturer directly?
Potentially, if the manufacturer accepts a compliant commercial payment and provides an appropriate invoice and business bank account. Verify that the beneficiary is connected to the supplier and that your bank or payment provider supports the required route and documentation.
Is a telegraphic transfer safe for paying a Chinese factory?
A telegraphic transfer is an established bank-payment method, but it does not protect the underlying purchase. Supplier identity, product quality, contract terms, inspection rights, payment milestones, and dispute recourse must be managed separately.
What information is needed for a bank transfer to China?
Expect to provide the payment currency and amount, beneficiary legal name and address, account number, beneficiary-bank name and SWIFT/BIC, payment purpose, and any required intermediary-bank information. The bank or provider may also request the commercial invoice and supporting import documents.
Should the first order remain under Alibaba Trade Assurance?
That depends on the cost and risk of the order. Keeping an early transaction inside a protected marketplace may provide a dispute process that a direct bank transfer does not. Compare that protection with the fees before moving payments outside the platform.
Can Quotable Payments send RMB to a Chinese supplier?
Quotable Payments supports approved supplier payments across many currencies and countries, but individual routes depend on eligibility, jurisdiction, receiving method, Recipient, and approved setup. Confirm current CNY availability with the payments team before relying on it for an invoice.